Typical Home Value in 2026: What Homes Cost Across the U.S.
October 6, 2026
7 minutes
Home values vary widely across the U.S. in 2026. A typical home value can be around $260,000 in some smaller Massachusetts cities, about $302,473 in Houston, approximately $309,300 across the South Carolina benchmark cited in the source material, and around $775,000 for a mid-tier California home. Los Angeles is substantially higher, with a citywide typical residential home value of about $951,035. Sub blogs Reviews Sub blogs Reviews Sub blogs Reviews Sources
These differences matter for buyers comparing markets. But a typical home value is a benchmark, not a guarantee of what a buyer will pay. Location, inventory, mortgage rates, property taxes, insurance, and neighborhood conditions can all affect the final cost of homeownership.
What Is a Typical Home Value?
A typical home value is a useful benchmark for understanding what a representative home costs within a particular market. It can help buyers compare cities, states, and neighborhoods before narrowing their search.
It is different from other housing measures:
| Housing measure | What it tells you | |
|---|---|---|
| Typical home value | A benchmark for home values within a market | |
| Median home price | The middle sale price when transactions are ranked | |
| Average home price | The arithmetic average of reported home prices | |
| Listing price | The price a seller is asking | |
| New-home sales price | The price of newly built homes sold during a specific period | |
| Assessed value | A value used for property-tax purposes |
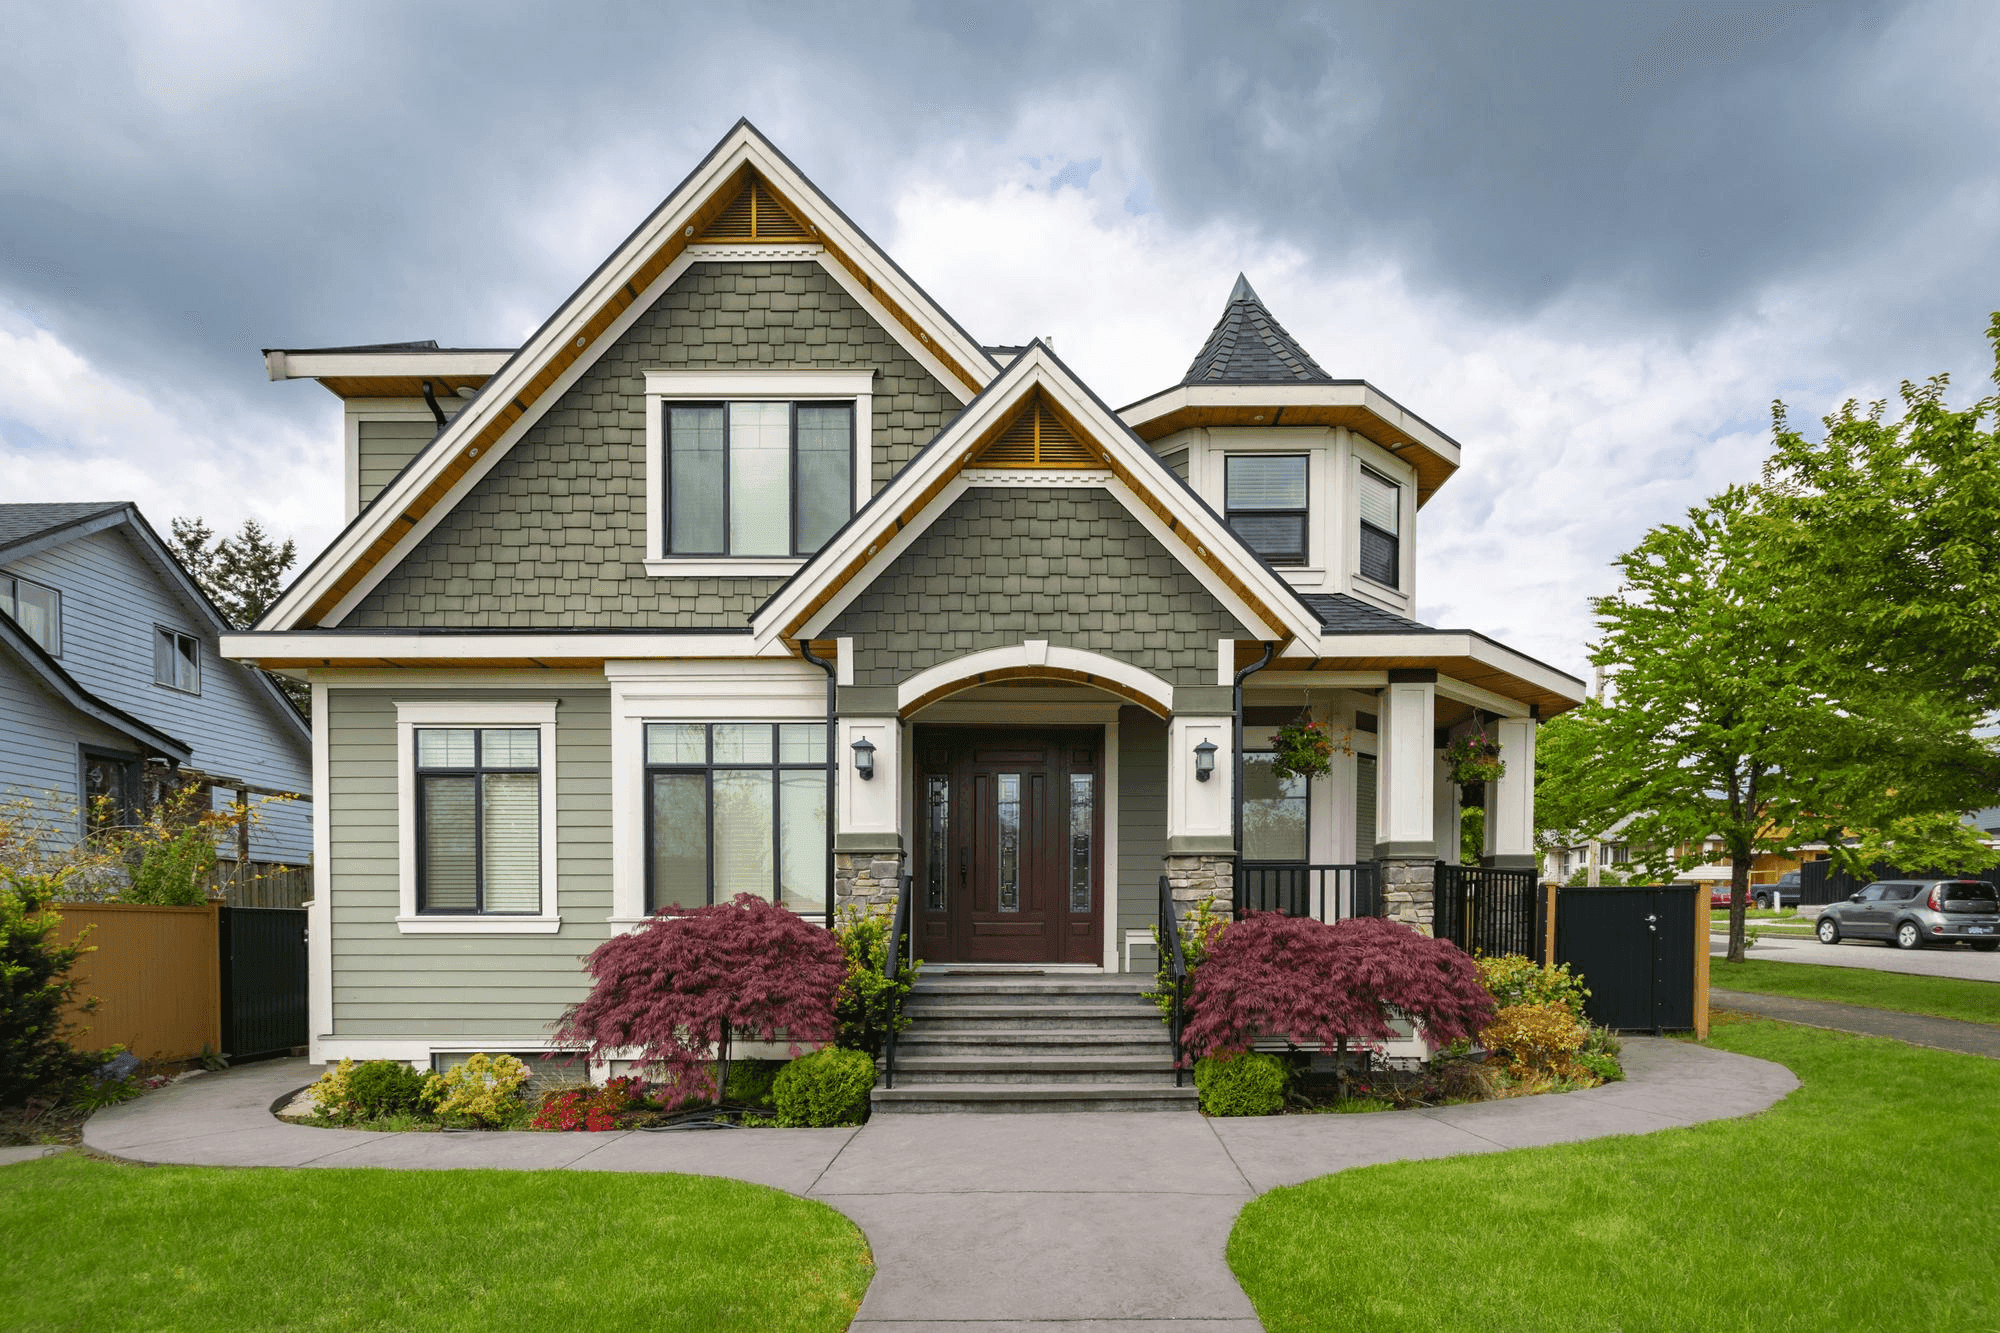
| Market | Typical Home Value |
|---|---|
| North Adams, Massachusetts | $260,429 |
| Springfield, Massachusetts | $265,192 |
| Pittsfield, Massachusetts | $296,022 |
| Holyoke, Massachusetts | $297,295 |
| Houston, Texas | $302,473 |
| South Carolina benchmark | ~$309,300 |
| Chicopee, Massachusetts | $312,658 |
| Massachusetts statewide benchmark | $667,265 |
| California mid-tier home | ~$775,000 |
| Los Angeles citywide | ~$951,035 |
The figures come from different geographic scopes and source methodologies, so they should be used as market-specific benchmarks rather than as a single standardized national dataset. Buyers comparing lower-cost markets can also review the most affordable places to live in Michigan to see how housing costs differ across another U.S. market.
Typical Home Value in Houston
Houston's typical home value was approximately $302,473, based on December 2025 data cited in the supplied 2026 housing guide. The market snapshot also reported substantial inventory and described Houston as a balanced market. Sub blogs Reviews
However, the citywide figure does not represent every Houston neighborhood. Values can vary considerably depending on location, schools, commute access, and local demand.
The source identifies stronger demand in areas such as West University, Bellaire, and Oak Forest, while Brookshire and Waller are identified among more affordable outlying markets. Sub blogs Reviews
For buyers, the Houston figure is best used as a starting benchmark. A property's actual cost can differ based on its neighborhood, condition, taxes, insurance, flood exposure, and other ownership expenses.
Typical Home Value in Massachusetts
Massachusetts has a statewide typical home value of approximately $667,265, but several cities in Western Massachusetts sit considerably below that level. Sub blogs Reviews
| City | Typical Home Value |
|---|---|
| North Adams | $260,429 |
| Springfield | $265,192 |
| Pittsfield | $296,022 |
| Holyoke | $297,295 |
| Chicopee | $312,658 |
This creates a significant gap between the statewide benchmark and some of the state's lower-cost housing markets.
The source also provides estimated monthly payments for these cities, but those estimates assume specific financing conditions and can change with mortgage rates, down payments, taxes, and insurance. Sub blogs Reviews
It is also important not to confuse the Massachusetts typical home value with the state's FY2026 average single-family assessed home value of $742,986 reported by the Massachusetts Division of Local Services. The latter is a property-tax assessment measure, not the same housing-value metric. Sources
Typical Home Value in South Carolina
The supplied South Carolina source places the state's home-value benchmark at approximately $309,300. It also shows that housing costs vary significantly between inland communities and coastal markets. Sub blogs Reviews
Selected affordable markets include:
| South Carolina Market | Typical Home Value |
|---|---|
| Bennettsville | ~84,758–149,000 |
| Dillon | ~$133,000 |
| Union | ~120,000–140,000 |
| Newberry | ~$175,000 |
| Orangeburg | ~120,000–140,000 |
The source notes that coastal housing can cost considerably more, with flood exposure, HOA fees, and proximity to the coast affecting the overall cost. Sub blogs Reviews
For buyers, this means a lower typical home value should not automatically be treated as a lower total housing expense. Insurance, taxes, financing costs, HOA fees, and closing costs can change the monthly budget.
Typical Home Value in Los Angeles
Los Angeles shows how much home values can vary within a single city. The citywide typical residential home value was approximately $951,035, with a reported 0.9% year-over-year decline in the source material.Buyers comparing housing costs with neighborhood characteristics can also review the safest neighborhoods in Los Angeles when evaluating different parts of the city.
Several neighborhoods included in the source have substantially higher typical values:
| Los Angeles Neighborhood | Typical Home Value | 1-Year Change |
|---|---|---|
| Pacific Palisades | $3.04M | -10.9% |
| Brentwood | $2.87M | +5.5% |
| Cheviot Hills | $2.47M | +3.2% |
| Beverlywood | $2.09M | -3.2% |
| Los Feliz | $1.84M | -2.7% |
| Mar Vista | $1.74M | -3.9% |
| Rancho Park | ~$1.70M | — |
| Encino | $1.43M | -1.2% |
| Westwood | $1.35M | +1.7% |
| Sherman Oaks | $1.28M | -2.5% |
| Los Angeles citywide | ~$951,035 | -0.9% |
The table illustrates why citywide figures should not be used as the expected price for every neighborhood. Some of the markets in the source are significantly above the Los Angeles citywide benchmark, while annual price changes also vary from one neighborhood to another. Sub blogs Reviews
Buying a Home? Get up to 1.5% Cash Back at Closing
Get pre-approved first, then start exploring homes knowing you can receive up to 1.5% of the home price back at closing.
California Home Values and Affordability
California sits at the higher end of the housing-value spectrum in the supplied data. The California Legislative Analyst's Office reports a mid-tier home price of approximately $775,000 in 2026. It also finds that California's bottom-tier homes are roughly 30% more expensive than the mid-tier home in the rest of the country. Sources
Affordability has also become more difficult:
- About 44% of California households are likely to qualify for a mortgage on a bottom-tier home in 2026.
- About 22% are likely to qualify for a mid-tier home.
- In 2019, the comparable figures were approximately 57% and 31%.
- A two-bedroom rental was estimated at about $2,700 per month in June 2026.
- Estimated monthly ownership costs for a mid-tier home were about $4,600, including principal and interest, property taxes, and insurance. Sources
These figures show why comparing typical home value with the full monthly cost of ownership is important.
How Property Taxes Can Change the Cost of a Home
Home value is only one part of the cost of owning property. Property taxes can add a significant recurring expense, particularly in high-value markets.
In California, Proposition 13 establishes a 1% base property-tax rate, while the supplied source estimates that many new buyers may pay approximately 1.1%–1.3% of the purchase price after applicable local bonds, parcel taxes, and other assessments. Sub blogs Reviews
The source also distinguishes this buyer planning range from the statewide blended effective rate of roughly 0.71%–0.76%, which reflects both newer and long-term property owners. Sub blogs Reviews
County-level home values can therefore produce very different estimated tax bills. Local assessments, Mello-Roos charges, bonds, and parcel taxes can further change the final amount.
Property taxes can also vary significantly between properties in the same market, as shown by how property tax bills can differ between two homes in Lakewood Ranch.
For that reason, buyers should use a parcel-specific estimate when calculating the expected property-tax expense rather than relying only on a statewide rate.
What the 2026 New-Home Market Shows
National new-home sales provide another useful piece of market context, although new-home sales prices should not be confused with typical home value.
According to the August 2026 U.S. Census Bureau and HUD release:
- New-home sales were running at a 684,000 annual rate in August 2026.
- There were approximately 483,000 new homes for sale.
- Supply stood at about 8.5 months.
- The median new-home sales price was $393,700.
- The median price was down 5.8% year over year. Sources
This provides national context for new construction, but it does not represent the typical value of all homes across the U.S.
What Causes Typical Home Values to Differ?
Several factors can cause the typical home value to vary significantly from one market to another.
Location and Neighborhood Demand
Homes near employment centers, schools, transportation, amenities, or established neighborhoods can command higher values than comparable properties elsewhere.
Housing Supply
Inventory affects how much choice buyers have and can influence pricing conditions. Markets with more available homes may give buyers more options when comparing properties.
Mortgage Rates
Mortgage rates affect how much buyers can afford to borrow and therefore influence purchasing power.
Taxes and Insurance
Two homes with similar purchase prices can have different monthly costs because property taxes, homeowners insurance, flood insurance, and other local expenses vary by location.
What Does the Typical Home Value Mean for Buyers?
A typical home value is best viewed as a starting benchmark, not a target purchase price.
Before deciding whether a market fits your budget, compare:
- Typical home value
- Current listing prices
- Mortgage costs
- Property taxes
- Homeowners insurance
- HOA fees, where applicable
- Maintenance costs
- Neighborhood and commute considerations
Buyers who are narrowing their search to Florida can also learn more about buying a home in Homestead, Florida, including the financing factors that can affect the overall cost of purchasing a home.
This approach gives buyers a clearer picture of what owning a home may actually cost.
Bottom Line
The typical home value in 2026 varies sharply across U.S. markets. Selected Massachusetts cities are below $315,000, Houston is around $302,473, the South Carolina benchmark is approximately $309,300, Massachusetts statewide is about $667,265, California's mid-tier home is around $775,000, and Los Angeles is approximately $951,035. Sub blogs Reviews Sub blogs Reviews Sub blogs Reviews Sources
For buyers, the most useful approach is to treat these figures as starting points. Comparing the typical home value with financing costs, taxes, insurance, inventory, and local conditions can provide a more realistic picture of what buying a home may cost in 2026.
FAQs
What is a typical home value?
A typical home value is a benchmark used to represent home values within a particular housing market. It can help buyers compare different locations, but it does not necessarily represent the price of every home for sale.
Is typical home value the same as median home price?
No. Typical home value and median home price are different measures and may be calculated using different methodologies. Buyers should check the definition and source behind each figure before comparing them.
Which U.S. markets have lower typical home values in 2026?
The supplied data show several lower-value markets in Massachusetts, including North Adams at $260,429 and Springfield at $265,192. Selected South Carolina communities also have substantially lower home values than the state's approximately $309,300 benchmark. Sub blogs Reviews Sub blogs Reviews
Does a lower typical home value mean a home is more affordable?
Not necessarily. Property taxes, insurance, mortgage rates, HOA fees, maintenance, and other ownership costs can increase the total monthly expense even when the purchase price is lower.
Why can home values differ so much within one city?
Neighborhood-level factors such as location, schools, employment access, housing supply, amenities, and local demand can create significant differences in home values within the same city.
Get the latest market trends, homebuying tips, and insider updates—straight to your inbox. No fluff, just the good stuff.
Further Reading
Article by
As a great communicator with excellent negotiation skills, I focus more on establishing unbreakable ties between my clients, as opposed to just helping them achieve their real estate dreams. As a representative of both buyers and sellers, I understand how to lead a transaction process to ensure that the needs of both are met. My track record speaks for itself. Since I ventured into the industry in 2013 as a realtor, I have not only helped many buyers land perfect homes, but I have also assisted tons of owners and investors build wealth.